Tag: Roof Insurance Claim

  • How to File a Claim for Roof Damage

    How to File a Claim for Roof Damage

    Dealing with a leaking or damaged roof is stressful enough without the added headache of navigating complex insurance paperwork. You want your home protected, but understanding the fine print can feel overwhelming. This guide simplifies the process, showing you exactly how to file a claim with insurance for roof damage efficiently and effectively.

    Immediate Steps: Safety and Documentation First

    Before you pick up the phone to call your insurer, your priority must be safety and evidence preservation. Insurance companies rely heavily on proof, and the quality of your initial documentation can significantly impact the speed and success of your claim.

    1. Ensure Safety and Mitigate Further Damage

    If the damage is severe, ensure no one is in immediate danger. Do not climb onto a wet or steeply pitched roof yourself; this is a job for professionals. However, you have a “duty to mitigate” further damage under most policies. This means you should take reasonable steps to prevent additional loss, such as placing tarps over leaks or moving furniture away from water intrusion. Keep receipts for any materials you buy for these temporary fixes, as they are often reimbursable.

    2. Document Everything Thoroughly

    Take clear, high-resolution photos and videos of the damage from multiple angles.

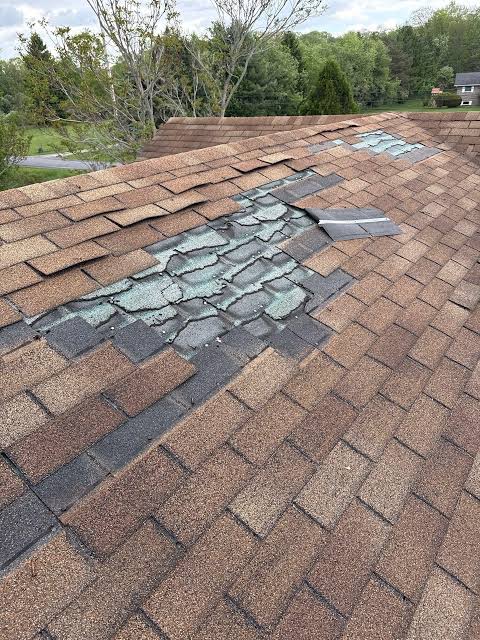
    • Exterior Shots: Capture missing shingles, dents, holes, or debris impact points. Use a zoom lens if safe to do so, or use a drone if you own one.
    • Interior Shots: Photograph water stains on ceilings, damaged insulation, or ruined personal property.
    • Date Stamps: Ensure your camera or phone settings include date and time stamps.

    According to industry data, claims with comprehensive visual evidence are processed 30% faster than those with sparse documentation. Create a digital folder specifically for this claim to keep everything organized.

    Understanding Your Policy Coverage

    Not all roof damage is covered. Before filing, you need to understand what your policy actually protects. Most standard homeowners insurance policies cover “sudden and accidental” damage caused by specific perils, but they exclude wear and tear.

    Covered vs. Non-Covered Causes

    Cause of DamageTypically Covered?Notes
    Wind/Hail StormsYesCommon in many US states; may have separate deductibles.
    Falling Trees/ObjectsYesIf a tree falls due to a storm, it’s usually covered.
    Fire/LightningYesStandard coverage in almost all policies.
    Age/Wear and TearNoGradual deterioration is considered maintenance.
    NeglectNoFailure to maintain the roof voids coverage.
    FloodingNoRequires separate flood insurance (FEMA).

    To better understand the historical context of property insurance standards, you can refer to general principles outlined on Wikipedia’s page on Property Insurance. However, always prioritize your specific policy document over general information.

    Check Your Deductible

    Your deductible is the amount you pay out-of-pocket before insurance kicks in. If your repair cost is $1,500 and your deductible is $2,000, filing a claim makes no financial sense. In fact, filing small claims can lead to higher premiums or even non-renewal of your policy. Always get a preliminary repair estimate before calling your insurer.
    How To File A Claim With Insurance For Roof Damage

    Step-by-Step: How to File the Claim

    Once you have determined that the damage exceeds your deductible and is likely covered, follow these precise steps to initiate the process.

    Step 1: Contact Your Insurance Provider

    Call your insurance company’s claims department immediately. Have your policy number ready. Be clear and factual about what happened.

    • Do say: “A hailstorm on November 1st caused significant shingle damage and interior leaking.”
    • Don’t say: “My roof is old and finally gave out.” (This implies wear and tear).

    Ask for a claim number and the name of the assigned adjuster. Request an email confirmation of your claim submission for your records.

    Step 2: The Adjuster’s Inspection

    The insurance company will send an adjuster to inspect the damage. This person works for the insurance company, not for you. Their goal is to assess the cost of repairs accurately according to their guidelines.

    • Be Present: Try to be home during the inspection. Walk through the damage with them.
    • Point Out Hidden Damage: Show them interior water damage, damaged gutters, or siding issues that might be related to the same event.
    • Provide Evidence: Share the photos and videos you took earlier.

    Step 3: Get Independent Contractor Estimates

    Do not rely solely on the insurance adjuster’s estimate. Hire a licensed, reputable roofing contractor to provide a detailed written estimate. Many contractors offer free inspections for insurance purposes.

    • Compare the contractor’s line items with the adjuster’s report.
    • Look for discrepancies in square footage, material costs, or labor rates.

    Step 4: Review the Settlement Offer

    The insurer will send a settlement letter detailing what they will pay. This is often split into two payments:

    1. Actual Cash Value (ACV): The depreciated value of your roof.
    2. Recoverable Depreciation: Paid after repairs are completed and invoices are submitted (if you have Replacement Cost Value coverage).

    If the offer seems low, do not accept it immediately. You have the right to negotiate.

    Negotiating a Fair Settlement

    It is common for the initial offer to be lower than the actual repair cost. Here is how to handle disputes professionally.

    Submit a Supplemental Claim

    If your contractor finds damage the adjuster missed, ask them to write a “supplemental report.” Submit this to your adjuster with photos. Most insurers have a process for reviewing supplements.

    Hire a Public Adjuster

    If the dispute is significant (e.g., thousands of dollars difference), consider hiring a public adjuster. They work for you, not the insurance company. They typically charge a percentage of the final settlement (usually 10–20%). For smaller claims, this fee might outweigh the benefit, so calculate carefully.

    Know Your Rights

    Each state has different regulations regarding insurance claims. Some states require insurers to respond within specific timeframes. If you feel you are being treated unfairly, you can contact your state’s Department of Insurance for assistance.

    FAQ Section

    1. Will filing a roof claim raise my insurance premiums?

    Yes, it is highly likely. Filing a claim signals to the insurer that you are a higher risk. Depending on your state and carrier, premiums could increase by 10–20% for several years. In some cases, multiple claims within a short period can lead to policy cancellation.

    2. How long do I have to file a claim for roof damage?

    Most policies require you to report damage “promptly” or within a reasonable time. While there isn’t always a strict statutory deadline like 24 hours, waiting months can give the insurer grounds to deny the claim, arguing that the delay prevented proper investigation or caused further damage. Aim to report within a few days of discovery.

    3. What if the adjuster says the damage is due to age?

    This is a common denial reason. If you believe the damage was caused by a specific event (like a storm) rather than age, provide evidence. Weather reports from the date of the storm, neighbor’s claims, and a professional opinion from your roofing contractor stating the damage pattern is consistent with wind/hail can help overturn this decision.

    4. Can I choose my own roofing contractor?

    Yes, you have the right to choose any licensed contractor you prefer. Insurance companies may recommend vendors from their network, but you are not obligated to use them. However, using a preferred vendor might streamline the payment process.

    5. What is the difference between ACV and RCV?

    Actual Cash Value (ACV) pays for the replacement cost minus depreciation (age and wear). Replacement Cost Value (RCV) pays the full cost to replace the roof with new materials of similar kind and quality, without deducting for depreciation. RCV policies are more expensive but offer better protection.

    Conclusion

    Learning how to file a claim with insurance for roof damage is about preparation, documentation, and persistence. By acting quickly, documenting thoroughly, and understanding your policy’s nuances, you can navigate the system with confidence. Remember, the goal is to restore your home to its pre-loss condition, not just to patch a leak.

    If you found this guide helpful, please share it on social media to help friends and neighbors protect their biggest investment. Stay safe, and keep your home secure!
  • How to Get Insurance to Pay for Roof Replacement: Reddit Tips

    How to Get Insurance to Pay for Roof Replacement: Reddit Tips

    Have you ever stared at your ceiling after a storm, wondering if your insurance company will actually cover the damage, or if you’ll be left footing the bill? It is a stressful situation that thousands of homeowners face every year, often feeling overwhelmed by complex policies and adjuster jargon. If you are searching for how to get insurance to pay for roof replacement Reddit threads are filled with real-world advice, but separating the noise from the actionable strategy is key to getting your claim approved.

    This guide synthesizes the most effective strategies shared by experienced homeowners, contractors, and public adjusters on community forums. We will walk you through the exact steps to document damage, communicate with your insurer, and ensure you receive the fair compensation you deserve.

    Understanding Why Claims Get Denied

    Before diving into the “how-to,” it is crucial to understand why insurance companies deny roof claims in the first place. According to industry data, a significant portion of denials stems from a lack of proper documentation or misclassification of the damage type.

    Insurance policies typically cover “sudden and accidental” damage, such as hail, wind, or falling trees. They generally do not cover wear and tear, lack of maintenance, or old age. This distinction is where many homeowners stumble.

    The “Wind vs. Wear” Debate

    One of the most common topics discussed in online communities is the difference between wind damage and natural deterioration. Adjusters are trained to look for specific patterns. For example, wind damage often shows up as missing shingles or creased tabs, while wear and tear might look like granule loss or curling edges.

    If an adjuster labels your damage as “maintenance-related,” your claim will likely be denied. This is why understanding the terminology and having proof of sudden impact is vital. You need to prove that a specific event caused the damage, not just the passage of time.

    How To Get Insurance To Pay For Roof Replacement Reddit

    Step-by-Step Guide to Filing a Successful Claim

    Getting your insurance to pay requires a methodical approach. Here is a breakdown of the process, optimized with tips frequently highlighted by successful claimants on discussion boards.

    1. Document Everything Immediately

    Do not wait for the insurance adjuster to arrive. The moment you suspect damage, start documenting.

    • Take Photos: Use a high-resolution camera. Take wide shots of the entire roof (if safe) and close-ups of specific damage points. Include photos of the surrounding area, such as fallen branches or debris, which can serve as context for the cause of damage.
    • Video Walkthrough: Record a video walking around your property, pointing out visible issues from the ground.
    • Interior Damage: Don’t forget to photograph any water stains on ceilings or walls inside your home. This links exterior roof damage to interior consequences, strengthening your claim.

    2. Review Your Policy Details

    Many homeowners skip this step, but it is critical. Look for the “Declarations Page” of your policy. Key terms to identify include:

    • Deductible: The amount you must pay out-of-pocket.
    • Coverage Limit: The maximum amount the insurer will pay.
    • Exclusions: Specific scenarios not covered (e.g., certain types of windstorms in hurricane-prone areas).

    Understanding these details prevents surprises later. If your deductible is $1,000 and the repair cost is estimated at $800, filing a claim might not be worth it due to potential premium increases.

    3. Hire a Reputable Roofing Contractor

    While you can file a claim yourself, having a professional opinion carries weight. Most reputable roofing companies offer free inspections.

    • Get a Detailed Report: Ask the roofer to provide a written report with photos, diagrams, and an estimate.
    • Look for Specific Language: The report should explicitly state that the damage was caused by a covered peril (like hail or wind), not age.
    • Avoid “Storm Chasers”: Be wary of contractors who door-knock immediately after a storm. Choose a local, established business with good reviews.

    4. File the Claim Promptly

    Once you have your documentation and contractor’s report, contact your insurance company. Provide them with:

    1. Date and time of the incident.
    2. Description of the weather event (e.g., “Hailstorm with golf-ball-sized hail”).
    3. Your photo evidence and the contractor’s preliminary report.

    Be honest and consistent in your description. Inconsistencies can raise red flags for fraud detection algorithms.

    Dealing with the Insurance Adjuster

    The insurance adjuster is the person who will inspect your roof and determine the payout. Their goal is to minimize the company’s loss, while your goal is to get full coverage. This dynamic often leads to tension.

    Tips for the Inspection Day

    • Be Present: Always be home during the inspection. Walk with the adjuster and point out the damage you documented.
    • Provide Your Evidence: Hand over your printed photos and the roofer’s report. Do not assume they will find everything on their own.
    • Stay Calm and Professional: Emotional outbursts rarely help. Stick to the facts.

    What If the Adjuster Denies the Claim?

    If the initial assessment results in a denial or a lowball offer, do not accept it immediately. Many Reddit users suggest requesting a re-inspection or hiring a public adjuster.

    A public adjuster works for you, not the insurance company. They charge a percentage of the settlement (usually 10-20%), but they often secure significantly higher payouts that cover their fee and then some. For large claims, this can be a worthwhile investment.

    Common Mistakes to Avoid

    Based on collective experiences shared in online forums, here are the pitfalls that lead to failed claims:

    MistakeConsequenceSolution
    Waiting too long to fileDamage worsens; policy deadlines missedFile within 24-48 hours of discovery
    Poor documentationLack of proof for causationTake timestamped, high-res photos immediately
    Admitting faultClaim denied based on negligenceStick to factual descriptions of weather events
    Using unlicensed contractorsInsurer rejects estimatesVerify license and insurance of your roofer

    External Resource for Further Reading

    For a deeper understanding of how property insurance works legally and structurally, you can refer to the general overview on Property Insurance – Wikipedia. This resource provides a broad context on risk management and indemnity principles that underpin your specific policy.

    FAQ Section

    1. Will my insurance premiums go up after a roof claim?

    In most cases, yes. Filing a claim signals to the insurer that you are a higher risk. However, if the damage was caused by a widespread natural disaster (like a hurricane affecting thousands of homes), insurers may be more lenient with rate hikes. Always weigh the cost of repair against the potential premium increase.

    2. Can I choose my own roofing contractor?

    Yes, you have the right to choose your own contractor. Insurance companies may recommend vendors from their network, but you are not obligated to use them. Ensure your chosen contractor is licensed, bonded, and insured.

    3. What if the insurance check is less than the repair cost?

    This is known as “depreciation.” Initially, insurers often pay the Actual Cash Value (ACV), which deducts for age and wear. Once repairs are complete and you submit receipts, they usually release the remaining Recoverable Depreciation to bring the total to the Replacement Cost Value (RCV). Make sure your policy includes RCV coverage.

    4. How long do I have to file a roof damage claim?

    Policy timelines vary, but most insurers require you to report damage “promptly” or within one year of the incident. Some states have specific statutes of limitations. Check your policy documents for the exact timeframe, but sooner is always better.

    5. Is it worth hiring a public adjuster?

    For small claims (under $5,000), it may not be cost-effective due to their fee structure. For large, complex claims involving total roof replacements or structural damage, a public adjuster can often negotiate a much higher settlement, making their fee worthwhile.

    6. What if my roof is old? Does insurance still cover it?

    Age alone does not void coverage, but it affects the payout. If your roof is near the end of its lifespan, the insurer may argue that the damage is due to wear and tear rather than a specific event. Strong evidence of sudden impact (like hail dents) is crucial in these cases.

    Conclusion

    Navigating the insurance claims process can feel like a battle, but being prepared changes the odds in your favor. By documenting damage thoroughly, understanding your policy, and communicating effectively with adjusters, you can significantly increase your chances of getting your roof replacement fully covered.

    Remember, the insights found when searching for how to get insurance to pay for roof replacement Reddit highlight one universal truth: knowledge is power. Don’t let the insurance company dictate the outcome without a fight. Gather your evidence, know your rights, and don’t hesitate to seek professional help if needed.

    If you found this guide helpful, please share it on social media to help other homeowners navigate their claims successfully. Have you had a recent experience with a roof claim? Share your story in the comments below!

  • How To Get Insurance To Pay For A New Roof

    How To Get Insurance To Pay For A New Roof

    Have you looked up after a storm and noticed missing shingles or a suspicious leak? Dealing with home repairs is stressful enough without the added headache of navigating complex insurance policies. If you are wondering how to get insurance to pay for a new roof, you are not alone; thousands of homeowners face this challenge every year, often feeling overwhelmed by the bureaucracy.

    The good news is that with the right preparation and knowledge, you can significantly increase your chances of a successful claim. This guide will walk you through the process, ensuring you understand your rights and the steps necessary to secure the funding you need for a safe, secure home.

    Understanding When Insurance Covers Roof Replacement

    Before filing a claim, it is crucial to understand why insurance companies approve or deny requests. Homeowners insurance is designed to cover “sudden and accidental” damage, not wear and tear.

    Covered Perils vs. Exclusions

    Most standard HO-3 policies (the most common type in the US) cover damage caused by specific events, known as perils. These typically include:

    • Windstorms: High winds that lift or tear off shingles.
    • Hail: Dents or cracks caused by hailstones.
    • Fire and Lightning: Structural damage from burns or strikes.
    • Falling Objects: Trees or branches falling onto the roof.
    • Weight of Ice/Snow: Collapse due to heavy accumulation.

    However, insurance will generally not cover damage resulting from:

    • Neglect: Failure to maintain the roof.
    • Age: Normal deterioration over time.
    • Poor Installation: Errors made during the original roofing job.

    According to the Insurance Information Institute, understanding your policy’s exclusions is the first step in managing expectations. If your roof is 20 years old and simply leaking due to age, a replacement is unlikely to be covered. However, if a storm accelerated that deterioration, you may have a case.

    How To Get Insurance To Pay For A New Roof

    Step 1: Document the Damage Thoroughly

    Evidence is everything in an insurance claim. Do not wait for the adjuster to arrive before gathering proof. The sooner you document the issue, the stronger your position will be.

    What to Photograph and Record

    1. Exterior Shots: Take clear, high-resolution photos of the damage from multiple angles. Use a drone if possible, or take photos from a safe vantage point. Capture close-ups of missing shingles, dents, or cracks.
    2. Interior Signs: Photograph water stains on ceilings, walls, or around windows. These prove that the exterior damage is affecting the livability of your home.
    3. Date and Time: Ensure your camera settings include timestamps. This proves the damage occurred recently, ideally correlating with a specific weather event.
    4. Temporary Repairs: If you had to put up a tarp to prevent further water intrusion, photograph this too. Keep receipts for any materials purchased for these emergency fixes.

    Pro Tip: Create a digital folder specifically for this claim. Back up all photos to cloud storage immediately to prevent data loss.

    Step 2: Review Your Policy Details

    Not all roofs are treated equally. Your payout depends heavily on the type of coverage you selected when purchasing your policy.

    ACV vs. RCV: Know the Difference

    FeatureActual Cash Value (ACV)Replacement Cost Value (RCV)
    DefinitionPays the current value of the roof minus depreciation.Pays the full cost to replace the roof with similar materials.
    DepreciationSignificant deduction based on age and condition.No depreciation deducted initially.
    Payout TimingSingle payment (lower amount).Two payments: Initial deposit + recoverable depreciation after work is done.
    Best ForOlder roofs where full replacement isn’t feasible.Newer roofs or those wanting full restoration.

    If you have an ACV policy, the insurance company will calculate the value of your roof based on its age. For example, if your roof has a 20-year lifespan and is 10 years old, they may only cover 50% of the replacement cost. With RCV, you get the full amount needed to replace it, provided you complete the repairs.

    Step 3: Hire a Reputable Roofing Contractor

    One of the most critical mistakes homeowners make is relying solely on the insurance adjuster’s assessment. Insurance adjusters work for the insurance company, not for you. Their goal is to minimize costs.

    Why You Need Your Own Estimate

    A licensed roofing contractor can provide an independent assessment of the damage. They can identify issues that an adjuster might miss, such as underlying deck damage or compromised flashing.

    • Get Multiple Quotes: Aim for at least three detailed estimates.
    • Check Credentials: Ensure the contractor is licensed, insured, and has good reviews in your local area.
    • Avoid “Storm Chasers”: Be wary of out-of-state contractors who appear immediately after a storm. They often lack local accountability and may perform subpar work.

    Your contractor can also meet with the insurance adjuster during the inspection. Having a professional present ensures that all damage is noted and discussed in real-time.

    Step 4: File the Claim and Meet the Adjuster

    Once you have your documentation and contractor estimates, it is time to file the claim. Call your insurance provider and provide them with the date of loss and a brief description of the damage.

    The Adjuster Inspection

    The insurance company will send an adjuster to inspect your property. Here is how to handle this meeting:

    1. Be Present: Always be home during the inspection. Walk the property with the adjuster.
    2. Point Out Damage: Show them the photos you took and point out specific areas of concern.
    3. Provide Your Contractor’s Report: Hand over the estimate from your roofer. This serves as a benchmark for the adjuster’s own estimate.
    4. Stay Calm and Factual: Avoid emotional arguments. Stick to the facts and the physical evidence.

    If the adjuster denies the claim or offers a lowball settlement, do not accept it immediately. You have the right to dispute the decision.

    Step 5: Negotiate the Settlement

    It is common for the initial offer to be lower than expected. This is where your preparation pays off.

    How to Counter a Low Offer

    • Request a Detailed Breakdown: Ask for the line-item estimate the adjuster used. Compare it with your contractor’s quote. Look for missing items, such as underlayment, flashing, or waste factors.
    • Submit Supplemental Claims: If you find discrepancies, submit a supplemental claim with photos and contractor notes explaining why additional funds are needed.
    • Invoke Appraisal Clause: If you cannot agree on the amount, most policies have an appraisal clause. This involves hiring an independent appraiser to resolve the dispute. Note that this can be costly, so use it as a last resort.

    Remember, negotiation is a standard part of the process. Insurance companies expect some pushback. Being polite but persistent is key to getting a fair settlement.

    FAQ Section

    1. Will my insurance premiums go up after a roof claim?

    Yes, in most cases, filing a claim can lead to higher premiums. However, this varies by state and insurer. Some states prohibit rate hikes for first-time weather-related claims. It is wise to ask your agent about potential rate impacts before filing.

    2. Can I choose my own roofing contractor?

    Absolutely. Your insurance company cannot force you to use their preferred vendor. You have the right to hire any licensed contractor you trust. Just ensure they are willing to work within the insurance guidelines for billing.

    3. What if my roof is old and the insurance says it’s just wear and tear?

    If the denial is based on age, it is difficult to overturn. However, if you can prove that a specific storm event caused new damage beyond normal wear, you may still get partial coverage. A professional roofing inspection report is essential here to distinguish between age-related issues and storm damage.

    4. How long do I have to file a roof insurance claim?

    Most policies require you to file “promptly,” but there is no universal federal deadline. State laws vary, but generally, you should file within one year of the damage. Delaying too long can give the insurer grounds to deny the claim due to lack of evidence.

    5. What is “recoverable depreciation”?

    If you have an RCV policy, the insurer initially pays the Actual Cash Value (depreciated amount). Once you complete the repairs and provide proof (invoices/receipts), they release the remaining balance, known as recoverable depreciation. This ensures the money is used for repairs.

    Conclusion

    Learning how to get insurance to pay for a new roof requires patience, documentation, and assertiveness. By understanding your policy, documenting damage thoroughly, and leveraging professional help from reputable contractors, you can navigate the claims process successfully.

    Remember, you are not just asking for a favor; you are claiming what you are entitled to under your contract. Stay organized, keep records of every communication, and do not hesitate to negotiate for a fair settlement.

    If you found this guide helpful, please share it on social media to help other homeowners navigate their insurance challenges. A well-informed community is better equipped to protect their homes and finances.

  • How To File A Roof Insurance Claim In Cumming GA

    How To File A Roof Insurance Claim In Cumming GA

    Dealing with roof damage is stressful enough without the added headache of navigating complex insurance paperwork. If you are a homeowner in Forsyth County, you likely know that Georgia weather can be unpredictable, ranging from severe hail storms to high winds that tear shingles loose. Knowing how to file a roof insurance claim in Cumming GA efficiently can save you thousands of dollars and significant peace of mind during a chaotic time.

    This guide is designed to walk you through the process with clarity and confidence. We will cover everything from immediate safety steps to negotiating with adjusters, ensuring you get the fair compensation you deserve under your policy.

    Why Acting Fast Is Critical in Cumming

    Time is not just money; it is coverage. Most homeowners insurance policies in Georgia have strict deadlines for reporting damage. While state laws vary, many insurers require you to report claims within 30 to 60 days of the incident. However, waiting too long can lead to denied claims if the insurer argues that subsequent weather events caused further damage.

    In Cumming, where spring thunderstorms and occasional winter ice storms are common, identifying the source of damage quickly is vital. Immediate action also prevents secondary issues like water intrusion, mold growth, and structural rot, which are often excluded from standard coverage.

    Step 1: Document Everything Before You Call

    Before you pick up the phone to call your insurance carrier, you need evidence. Insurance adjusters rely heavily on proof. Without it, your claim may be undervalued or denied.

    Take High-Quality Photos and Videos

    Do not just take one photo from the ground. You need a comprehensive visual record:

    • Wide Shots: Capture the entire house from all four sides to show context.
    • Close-Ups: Focus on specific damage points, such as missing shingles, dented vents, or cracked flashing.
    • Interior Damage: Photograph any water stains on ceilings, walls, or damaged personal property inside the attic.
    • Date Stamps: Ensure your camera or phone settings include date and time stamps.

    Create a Written Inventory

    Write down a detailed description of what happened. Include:

    • The date and approximate time of the storm.
    • Weather conditions (e.g., “golf ball-sized hail,” “winds estimated over 50 mph”).
    • Any immediate actions you took to mitigate damage (such as placing tarps).

    Pro Tip: Keep a copy of this documentation in a cloud storage service. This ensures you have access even if your home suffers severe damage.

    Step 2: Review Your Policy Details

    Not all roof damage is covered. Understanding your specific policy is crucial before filing. In Georgia, many policies have moved toward Actual Cash Value (ACV) rather than Replacement Cost Value (RCV) for older roofs.

    • RCV Policies: Pay the cost to replace the roof with new materials, minus your deductible.
    • ACV Policies: Pay the current value of the roof, accounting for depreciation based on age and wear.

    Check your policy for any “wind/hail deductibles.” In hurricane-prone or storm-heavy areas like parts of Georgia, these deductibles can be higher than your standard all-peril deductible. Knowing this number beforehand helps you decide if filing a claim is financially viable.

    Step 3: Contact Your Insurance Provider

    Once you have your documentation and policy details ready, contact your insurer. Be clear, concise, and factual.

    1. Report the Incident: State that you wish to file a claim for storm damage.
    2. Provide Documentation: Offer to send the photos and inventory you prepared.
    3. Get a Claim Number: Write this down immediately. It is your reference point for all future communications.
    4. Ask About Timelines: Inquire about when an adjuster will be assigned and when they expect to visit.

    During this call, avoid speculating about the cause of damage if you are unsure. Stick to the facts: “I noticed damage after the storm on [Date].”

    Step 4: Prepare for the Adjuster’s Visit

    The insurance adjuster is the person who determines the extent of the damage and the payout amount. Their goal is to assess liability accurately, but remember, they work for the insurance company, not for you.

    Do’s and Don’ts During the Inspection

    DoDon’t
    Be present during the inspection.Leave the adjuster alone to walk the property.
    Point out all visible damage.Argue aggressively or become emotional.
    Provide your own photos and notes.Assume the adjuster sees everything from the ground.
    Ask questions about their findings.Sign any settlement documents immediately.

    In Cumming, local adjusters are familiar with common roofing materials like architectural shingles and metal roofs. However, they may miss subtle signs of wind uplift or hail bruising. Having a professional roofer present during the inspection can be invaluable.

    Step 5: Hire a Reputable Local Roofer

    While you cannot force the insurance company to use a specific contractor, hiring a trusted local expert is one of the smartest moves you can make. A reputable roofing company in Cumming can act as your advocate.

    Look for contractors who:

    • Are licensed and insured in Georgia.
    • Have experience dealing with insurance claims.
    • Offer free inspections and detailed estimates.

    A professional roofer can identify damage that an adjuster might overlook. They can also provide a scope of work that matches industry standards, ensuring you aren’t short-changed on materials or labor costs. For more information on construction standards, you can refer to general building guidelines available on Wikipedia.

    Step 6: Review the Settlement Offer

    After the inspection, the insurance company will send a settlement offer. Do not accept the first offer blindly.

    Compare the insurer’s estimate with the quote from your chosen roofer. Look for discrepancies in:

    • Square footage calculations.
    • Material quality (e.g., matching shingle brands).
    • Labor costs and overhead.
    • Waste removal fees.

    If there is a significant gap, you have the right to dispute the claim. Provide your roofer’s detailed estimate to your adjuster and request a re-evaluation. This process is known as “supplementing” the claim.

    How To File A Roof Insurance Claim In Cumming Ga

    Common Challenges in Cumming Claims

    Filing a claim in Forsyth County comes with unique challenges. One major issue is the age of the roof. Many insurers in Georgia are becoming stricter about roofs older than 15–20 years. They may argue that damage is due to “wear and tear” rather than a specific storm event.

    To combat this, ensure your roofer provides evidence of sudden, accidental damage. Hail hits, for example, leave distinct marks that differ from natural aging. Wind damage often shows lifted shingles or broken seals, which are not typical of gradual deterioration.

    FAQ Section

    1. Will my insurance rates go up if I file a roof claim in Cumming?

    It depends on your carrier and claim history. A single weather-related claim may not increase your premium significantly, especially if it was a widespread event affecting many neighbors. However, multiple claims within a few years can lead to higher rates or non-renewal. Always weigh the repair cost against your deductible and potential rate hikes.

    2. How long does the roof insurance claim process take in Georgia?

    Typically, the process takes between 2 to 4 weeks. Simple claims may be resolved faster, while complex disputes or large-scale storm events can delay adjustments due to high volume. Georgia law requires insurers to acknowledge claims promptly, but investigation times can vary.

    3. What if the insurance adjuster denies my claim?

    If your claim is denied, request a written explanation citing the specific policy language. You can then hire a public adjuster or an attorney specializing in insurance disputes. Often, providing additional evidence from a licensed roofing contractor can overturn a denial.

    4. Can I choose my own roofing contractor?

    Yes. In Georgia, you have the right to choose any licensed contractor to repair your roof. The insurance company cannot force you to use their “preferred” vendors. However, using a preferred vendor might streamline the payment process, though it may limit your negotiation power.

    5. What is the difference between ACV and RCV in my payout?

    Actual Cash Value (ACV) pays you the depreciated value of your roof at the time of loss. Replacement Cost Value (RCV) pays the full cost to replace the roof with new materials. If you have an RCV policy, you may receive an initial check for the ACV amount, with the remaining “recoverable depreciation” paid after repairs are completed and invoices submitted.

    Conclusion

    Learning how to file a roof insurance claim in Cumming GA doesn’t have to be overwhelming. By documenting damage thoroughly, understanding your policy, and partnering with a trusted local roofer, you can navigate the system effectively. Remember, the goal is to restore your home to its pre-loss condition, not just to patch it up.

    Stay organized, ask questions, and don’t hesitate to advocate for yourself. If you found this guide helpful, please share it with your neighbors in Cumming and Forsyth County. Helping others prepare can strengthen our community’s resilience against future storms.